How rates work
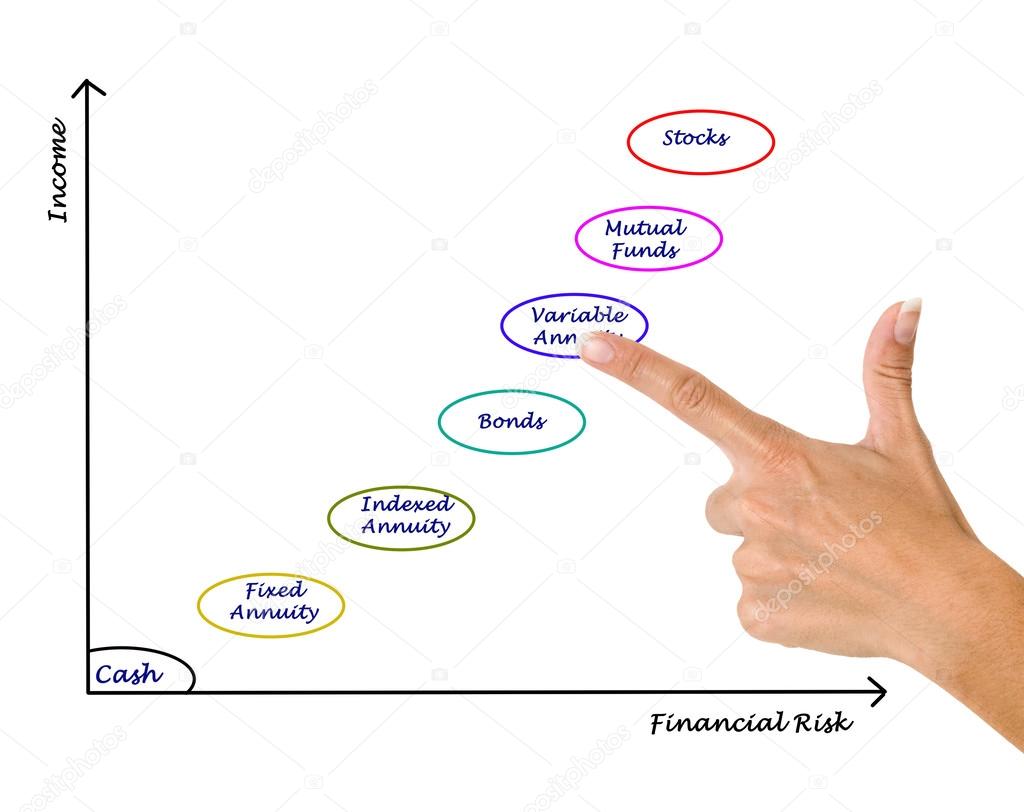
• Fixed (MYGA): Guaranteed interest for 2–10 years. Typical ranges vary by term; ask for current rates.
• Indexed (FIA): Interest credits based on an external index with caps, spreads, or participation rates. No direct market losses to principal.
Common fees
• Mortality & expense (sometimes none on fixed).
• Rider fees for income, enhanced death benefit, or long-term care features (typically 0.9%–1.5% of benefit base).
• Optional allocation or strategy fees on some FIAs.
Surrender periods
• Most contracts include a declining schedule (e.g., 10%, 9%, 8%, …) over 7–10 years.
• Free withdrawals often allow up to 10% of account value annually after year 1 without surrender charge.
Example schedule
Year 1: 10% | Year 2: 9% | Year 3: 8% | Year 4: 7% | Year 5: 6% | Year 6: 5% | Year 7: 4% | Year 8: 3% | Year 9: 2% | Year 10: 1%
What to evaluate
• Rate guarantees and renewal rate history.
• Index strategy mechanics (cap/participation/spread) and liquidity rules.
• Total cost of riders vs. expected benefit.
• Financial strength of the issuing insurer.
- You want a portion of your savings protected from market declines.
- You value predictable income and may want lifetime payout options.
- You won’t need to access the funds beyond the free-withdrawal amount during the surrender term.
- You prefer tax-deferred growth on non-qualified money.
- You want to transfer longevity risk to an insurer.
- You need full liquidity or expect large withdrawals soon.
- You are seeking high-growth, high-risk investments.
- Your time horizon is shorter than the surrender period.
- You can secure better employer benefits (e.g., immediate match) with the same dollars.
Explore complementary options on our Term Life Insurance and Financial Analytics pages.
Tax-deferred growth
Earnings inside an annuity grow tax-deferred. You pay taxes when you withdraw gains.
How withdrawals are taxed
Non-qualified contracts typically use last-in, first-out (LIFO) rules—gains come out first and are taxed as ordinary income. Qualified annuities inside IRAs/401(k)s are fully taxable when distributed.
RMDs and age rules
Qualified funds are subject to Required Minimum Distributions per current law. Early withdrawals before applicable age may incur penalties.
1035 exchanges
You may be able to exchange one annuity for another without current taxation through a 1035 exchange. Evaluate surrender charges, new fees, and benefits before proceeding.
We are not tax advisors. Consider consulting a tax professional for your situation.
What you’ll receive
- Personalized annuity comparison (rates, caps/participation, surrender schedules).
- Income projections with and without riders.
- Liquidity review and penalty-free withdrawal options.
- Carrier strength and ratings summary.
No pressure, no obligation.
Annuity products and features vary by insurer and state. Guarantees are subject to the claims-paying ability of the issuing insurance company. Rates and terms change frequently; always refer to the official contract and disclosure documents for details. This page is for educational purposes and is not a recommendation. Suitability depends on your objectives, risk tolerance, time horizon, and liquidity needs. Read the contract and prospectus/statement of understanding (if applicable) before purchasing.